On October 21, 2026, the U.S. Office of the Comptroller of the Currency (OCC, the federal banking regulator) issued the final GENIUS Act rule, deleting the provision in the proposal that "third-party payment of interest on behalf of the issuer is presumed illegal," while refusing to provide a safe harbor for stablecoin reward programs on platforms such as Coinbase, PayPal, and Kraken.
This document, exceeding 700 pages, is the first completed core GENIUS Act rule among federal banking regulators.
Coinbase One's USDC rewards annualize at about 3.75%, PayPal's PYUSD at about 4%, and Kraken's USDG at up to about 4.5%. Over the same period, the average savings rate on insured U.S. deposit accounts is about 0.38%. These figures are not compliant yields as determined by the OCC; whether they hold up must be judged case by case.
The market reads it as a green light; the rule says no judgment for now
During the proposal stage, the OCC wanted to establish a "rebuttable presumption": if an affiliate or third party pays on behalf of the issuer, it is first presumed to be a violation, with the parties bearing the burden to rebut. The final draft removed this provision on the grounds that the market is still in an early stage.
This move is easily read as a relaxation. In the same document, the OCC made several things clear. There is no grandfather clause for existing rewards; Congress knew these programs existed when legislating, which does not equal approval of their compliance. DeFi (decentralized finance), white-label arrangements, and small payments all have no category exemption—"interest under another name is still interest."
There is another layer of jurisdictional boundaries that is widely misunderstood. The OCC regulates payment stablecoin (tokens claiming to be pegged to the U.S. dollar and used for payments) issuers within its jurisdiction, certain foreign issuers, and certain custody businesses; it does not license exchanges. The constraints on Coinbase and Kraken reward products are indirect, transmitted through licensed issuers and their third-party relationships.
The Ban Hinges on Four Words: "Solely by Virtue of Holding"
The statutory text prohibits issuers from paying interest or yield to holders "solely by virtue of holding, using, or retaining a payment stablecoin." The final rule splits this sentence into two variables: who pays, and why they pay.
If the issuer pays out of its own funds and the reason is simply "you hold this coin," it falls within the prohibition. If an affiliate or exchange pays on its behalf and the payment is substantively still tied only to holding, it may likewise be deemed circumvention. If the payment is at least partly for transaction incentives, genuine services, or other independent reasons, it may fall outside the prohibition.
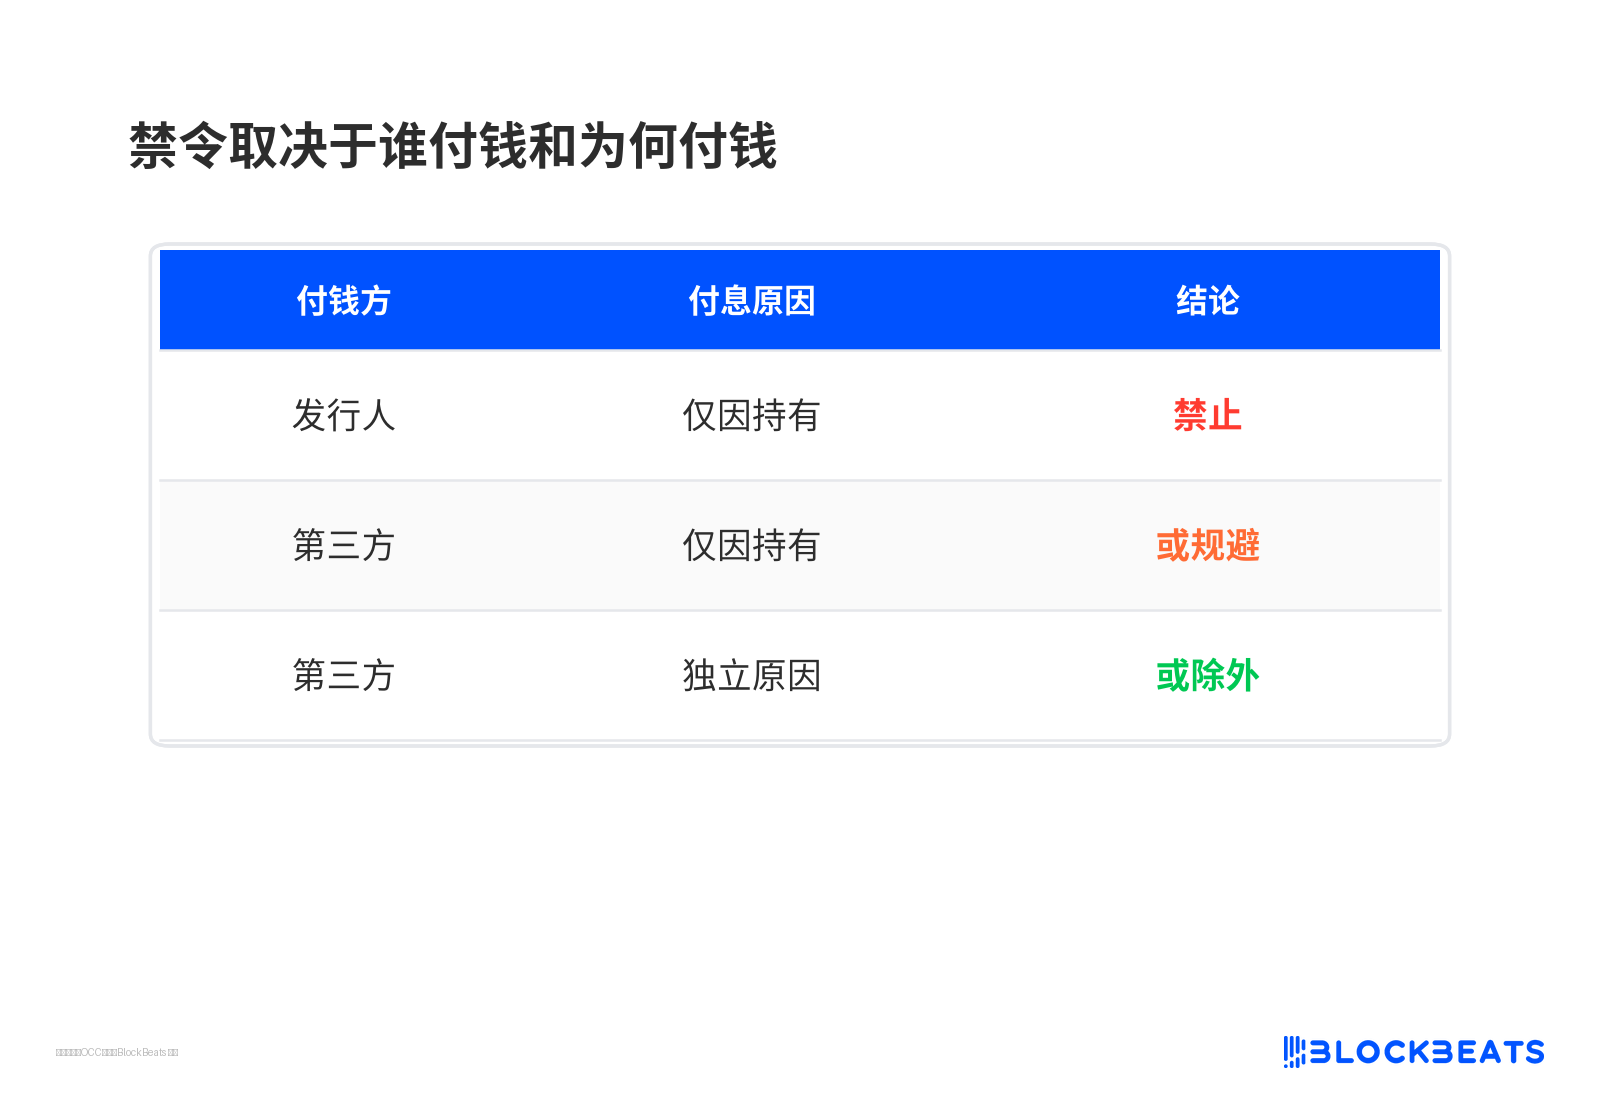
A legislative principle thus becomes a factual determination. Deleting the presumption lowers the issuer's evidentiary burden but does not bring certainty. The OCC retains anti-circumvention authority and can reapply the statute based on specific facts—the flexibility of the rule is itself a stance.
Banks Want a Lockdown, Trading Platforms Want an Endorsement, Analysts See Only Uncertainty
Rob Nichols, president and CEO of the American Bankers Association, criticized in a statement that the final rule departs from the original proposal, effectively preserving the status quo for crypto platforms and contravening Congress's intent to protect local lending. Issuers can still use affiliates or exchanges to offer "economically equivalent yield," draining deposits from the banking system.
Coinbase Chief Policy Officer Faryar Shirzad takes the opposite view. He believes the rule interprets the congressional text and sets capital requirements based on actual risk, building a durable framework for dollar stablecoins. Circle Chief Strategy Officer Dante Disparte called it a translation of legislative leadership into clear, enforceable regulatory standards.
Jaret Seiberg, head of Washington research at TD Cowen, is more sober in his assessment. He sees it as net negative for banks because platforms' ability to pay yield has not been fully shut off. Case-by-case review creates uncertainty, and ultimately the Supreme Court may have to define which yields are legal.
What the three sides are really arguing about is the same thing: whether third-party rewards are competitive space Congress deliberately left open, or should be presumed to be circumvention. The OCC's choice is to side with neither, pushing the answer to subsequent enforcement.
The 4% Answer Awaits License Review
Starting January 18, 2027, issuing payment stablecoins without a license will generally constitute a criminal offense. Existing U.S. issuers may apply for an exemption of up to 12 months, and the OCC has said it will generally favor approval unless stronger grounds for denial exist. But the application window has not yet opened, pending approval of the relevant information collection plan.
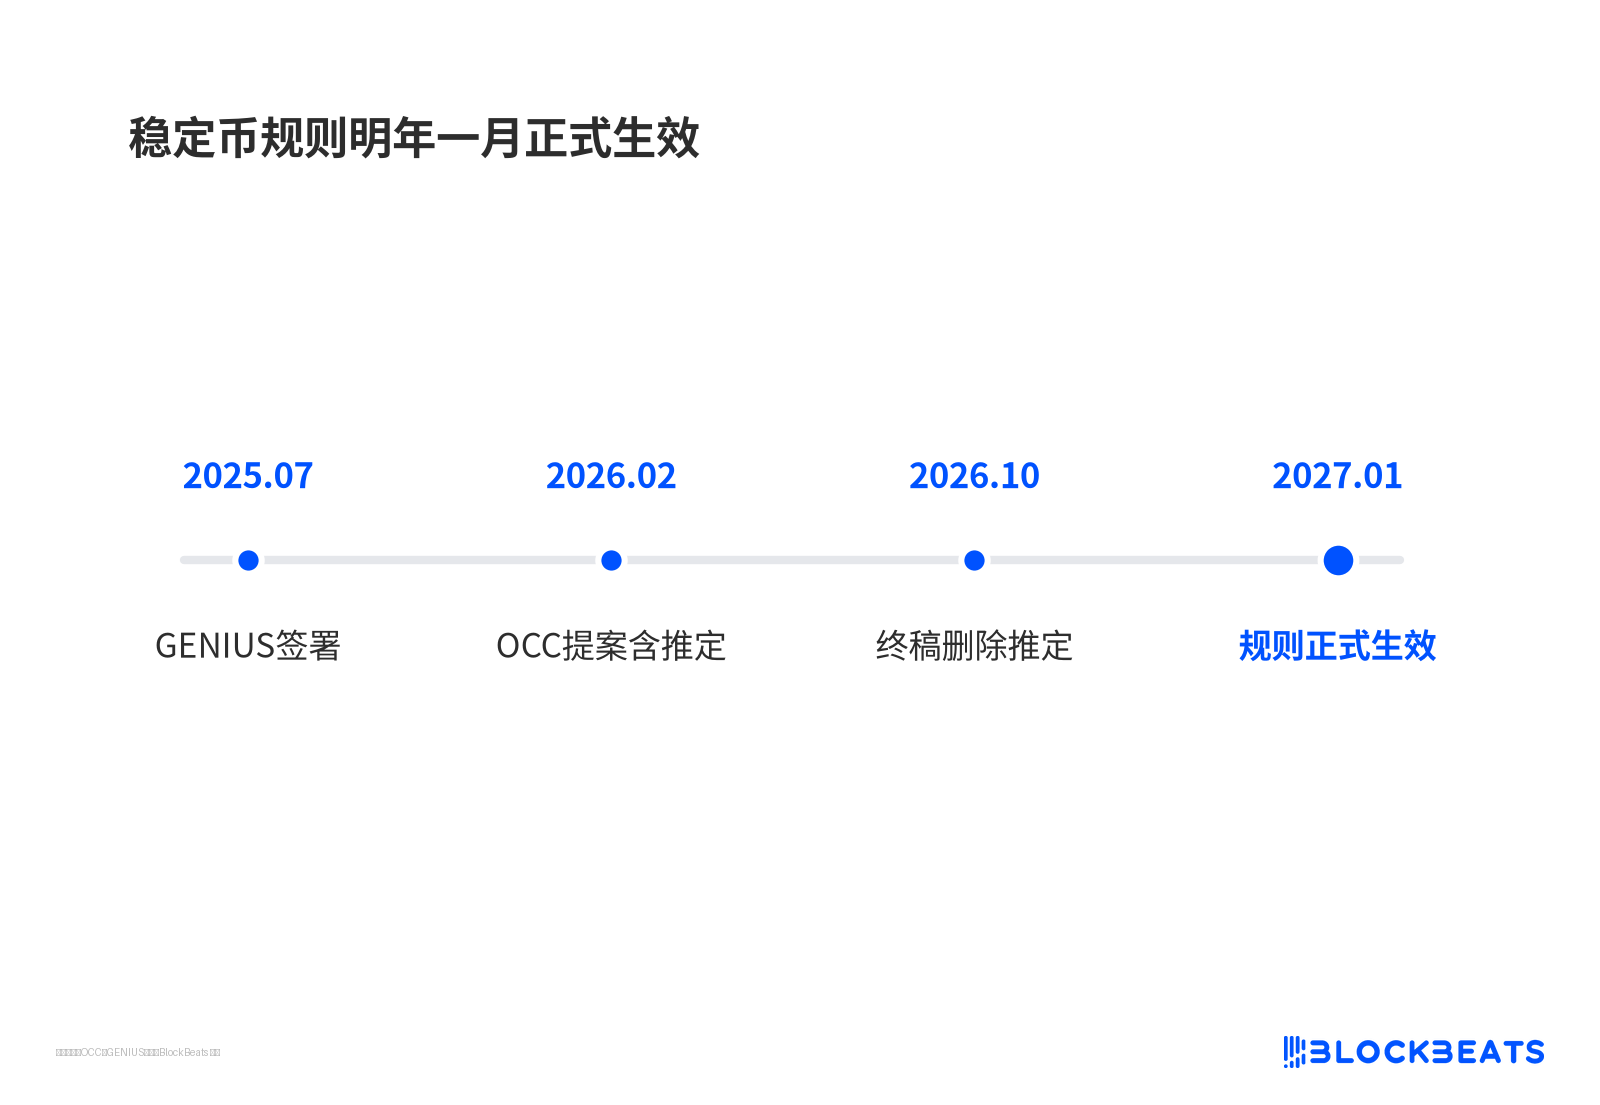
How the first batch of licenses is reviewed will be the first real signal. If the OCC, when assessing issuer qualifications, folds trading platform reward arrangements into the "solely by virtue of holding" test, those 4% products will face a concrete ruling for the first time.
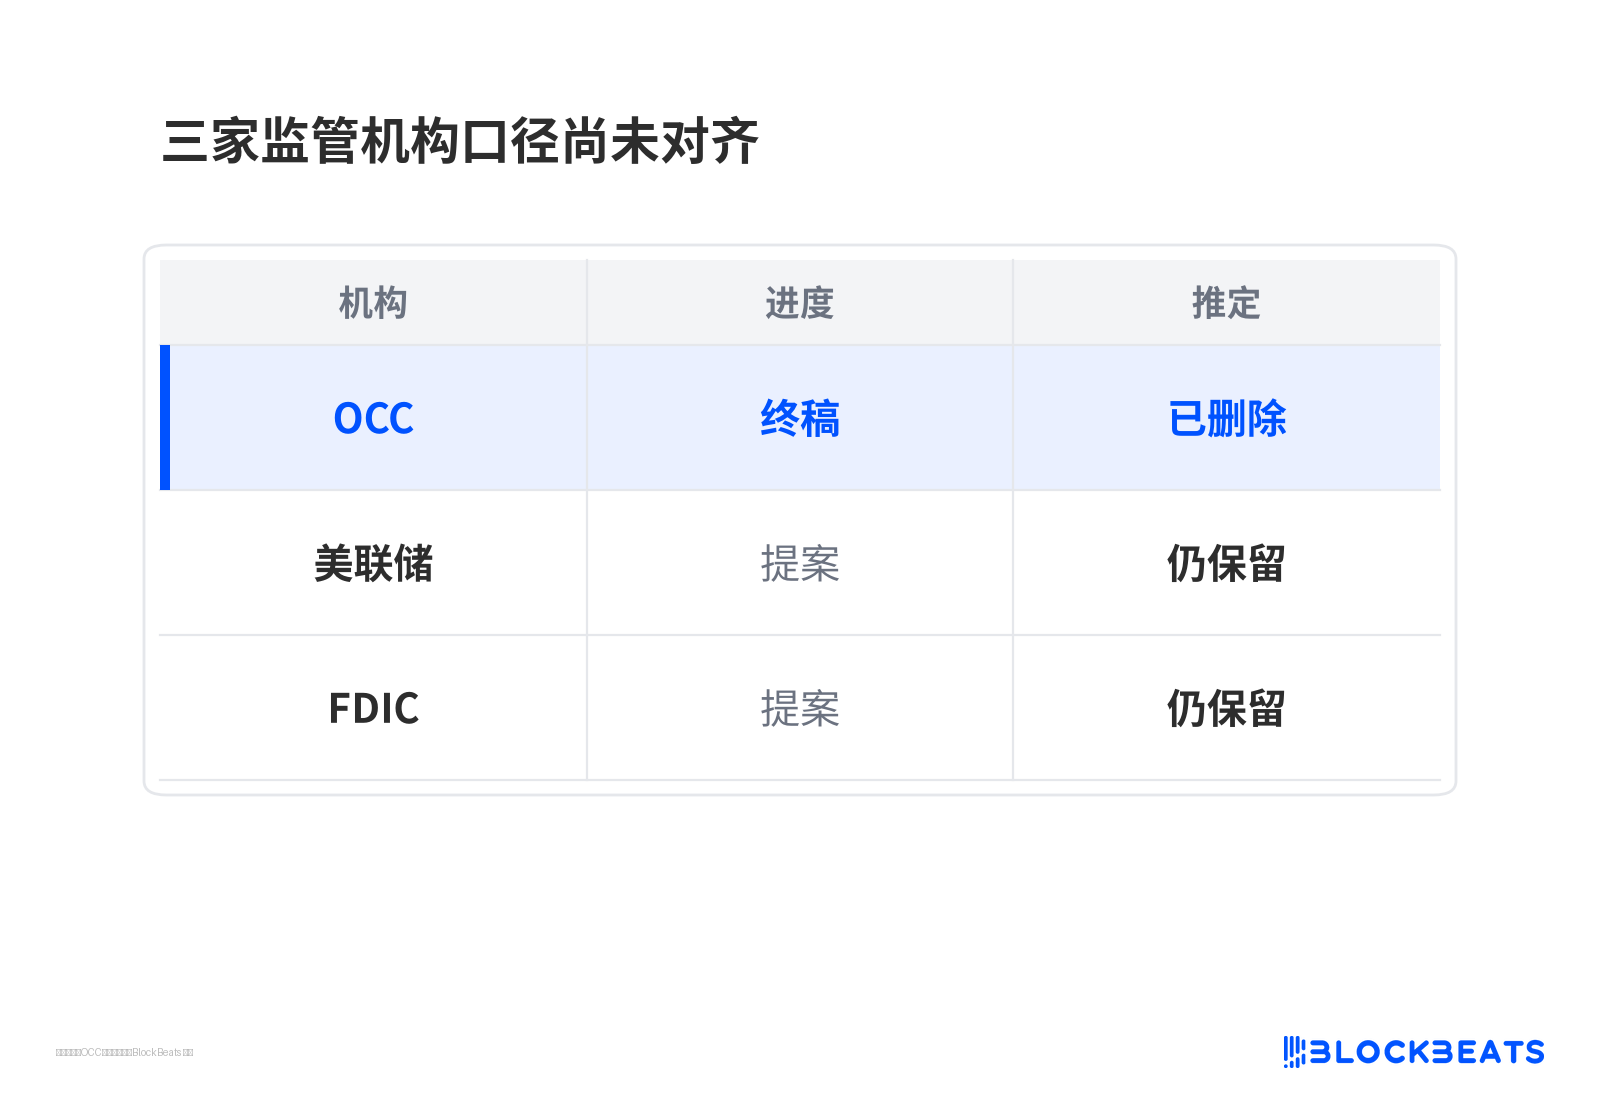
Another variable comes from the institutional gap. The Federal Reserve and FDIC's corresponding rules have not yet been finalized, and according to industry media reports, both agencies' earlier proposals contained similar presumptions. Once the three agencies' standards diverge, compliance costs and arbitrage space will both be reshuffled.
The Clarity Act failed to advance in the Senate in September 2026, and the related disputes may still return through litigation or new legislation. This rule covers only the OCC's jurisdiction; the rest of the ecosystem is handled separately by the other two agencies and the Treasury Department's anti-money laundering and sanctions rules.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia
