Claude developer Anthropic has finally put its books in front of the public market. On October 26, the company submitted a public version of its S-1 prospectus to the U.S. Securities and Exchange Commission, applying to list on Nasdaq under the ticker "ANT," with the offering price and share count left blank.
Flipping through the document, what makes you stop most is the starkly different impressions given by the income statement and the cash flow statement. Net loss for the first half was about $80.7 billion, yet operating activities brought in about $3.9 billion in net cash inflow. How could the same company's business show these two numbers at the same time?
The answer lies in the composition of the loss. However, before unpacking those financial instruments, there is another change closer to Claude's day-to-day business. According to the quarterly statements disclosed in the prospectus, second-quarter revenue already exceeded operating expenses for the quarter.
Can Claude's revenue already cover quarterly expenses?
First, look at the quarterly operating performance table. Second-quarter operating profit reached $974 million, with an operating margin of about 8.4%. Converted by revenue ratio, for every sale recognized in the quarter, after deducting the operating expenses listed in the statements, a small amount of operating profit was already left.
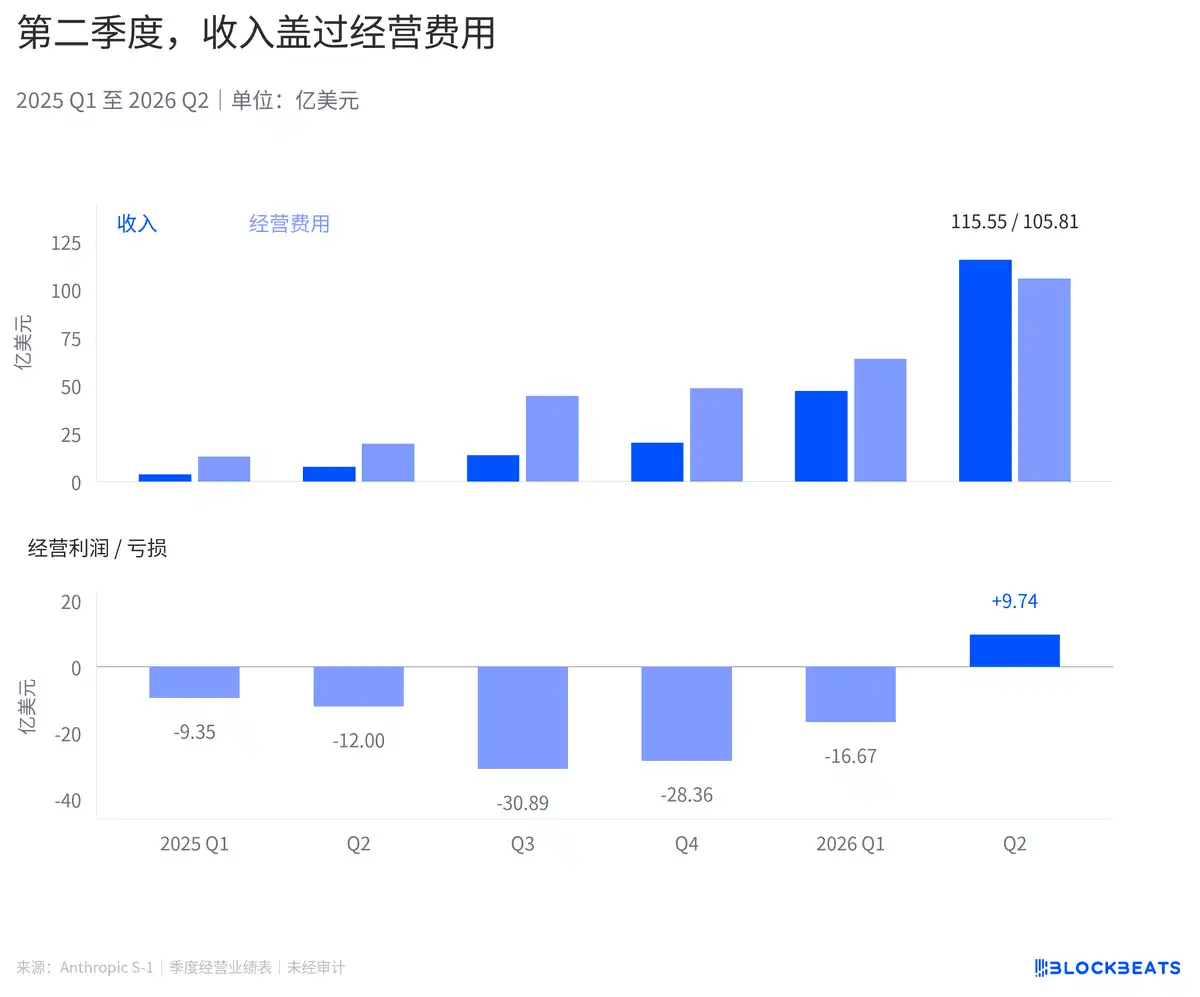
From the chart above, it can be seen that the reason for crossing the break-even line is that revenue growth outran expenses. Bills for compute and personnel are still rising, and sales and partnership expenses are also expanding, but revenue is climbing faster. This is a different kind of operating change from squeezing out profit after cutting investment.
But looking back at the entire first half, operating activities still recorded a loss of about $693 million. The operating profit earned in the second quarter has not yet fully covered the gap left by the first quarter. Looking only at the latest quarter versus only the half-year total will give different intuitions.
The company changed its expense presentation in the prior year, shifting items originally classified by function such as cost of revenue and research and development to classification by nature such as compute and personnel, with historical periods also restated under the new method. Gross profit is no longer separately presented.
So the question of how much gross profit can be retained for each additional model service sold is unknown.
Since operations are near break-even, where does the huge net loss come from?
In the income statement, after the operating results there is a large block of gains and losses on financial instruments. The company previously raised financing through convertible bonds and other means, and these instruments need to be remeasured under applicable accounting rules. The prospectus states that changes in fair value of convertible bonds and other instruments were mainly driven by rising enterprise valuation.
Think of it as two ledgers updated simultaneously. One records the results of Claude selling services, using compute power, and paying personnel costs; the other records the gains and losses from financing arrangements that must be recognized as valuations change. Losses in the second ledger also flow into the final net loss.
In the cash flow statement, the company adds back fair value changes related to convertible notes, derivative liabilities, and simple agreements for future equity, amounting to approximately $72.4 billion. Such add-backs eliminate the impact of non-cash items in the income statement; no equivalent amount of cash therefore enters the bank account.
Based on the cash flow statement, these working capital changes contributed a total net inflow of approximately $1.168 billion in the first half. The company noted in its management discussion that cash flow improvement was also affected by the timing of supplier payments and customer collections. Collecting payments earlier, delaying payments, or drawing down previously prepaid compute power can all make cash performance in a given period look better than profit performance.
Therefore, positive operating cash flow has real significance, indicating that the results of operating receipts and expenditures have changed during the period. It still needs to be read in the context of collection and payment rhythms, and cannot alone prove that the same cash-generating capacity can be maintained in every future quarter.
With so much cash on the books, is there enough compute power for the future?
Next, look at where the funds came from. The cash flow statement in the prospectus shows net cash inflow from financing activities of approximately $110.8 billion in the first half. Compared with cash generated from operations, financing was the primary source of additional funds during this period.
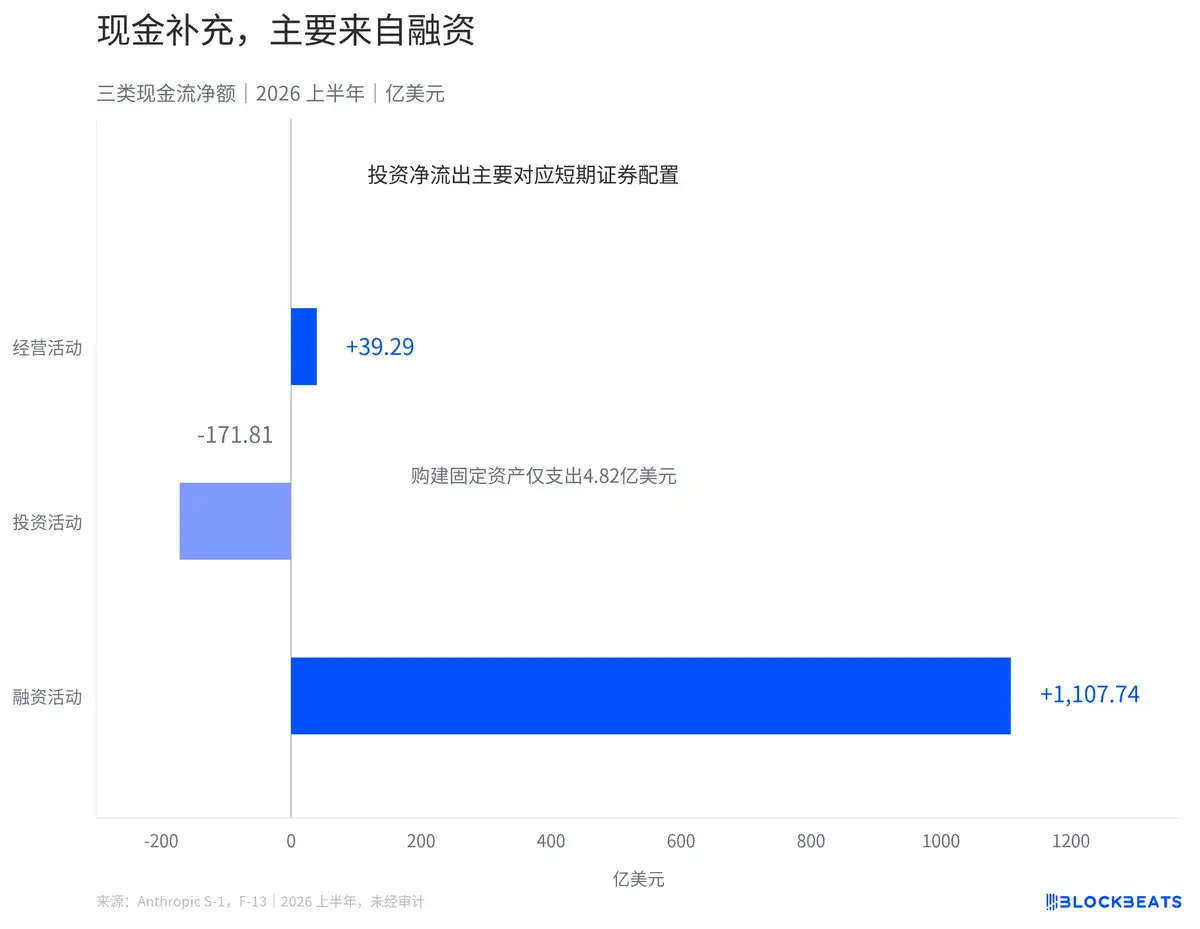
Net cash outflow from investing activities did not go toward buying servers and data centers; a substantial portion was used to purchase short-term securities.
Cash expenditures for the purchase and construction of fixed assets during the same period were $482 million, far less than the total net investing outflow. Purchasing short-term securities increases investing expenditures on the cash flow statement, but it cannot be concluded from this that the money has been consumed as compute infrastructure costs. Compute costs for training models also cannot be simply equated with expenditures on the purchase and construction of fixed assets.
The prospectus discloses that cash, cash equivalents, and short-term investments totaled approximately $131.7 billion at mid-year. Understanding this reserve requires keeping in mind both its sources and uses—financing supplemented today's cash pool, while future contractual arrangements determine when these funds must be paid out.
Among the purchase commitments disclosed in the notes, non-cancelable agreements with remaining terms exceeding one year had risen to approximately 4.9 times the prior year-end level after six months. These figures reflect supply obligations that are already locked in—even if revenue slows in the short term, contracts may not be able to scale down accordingly.
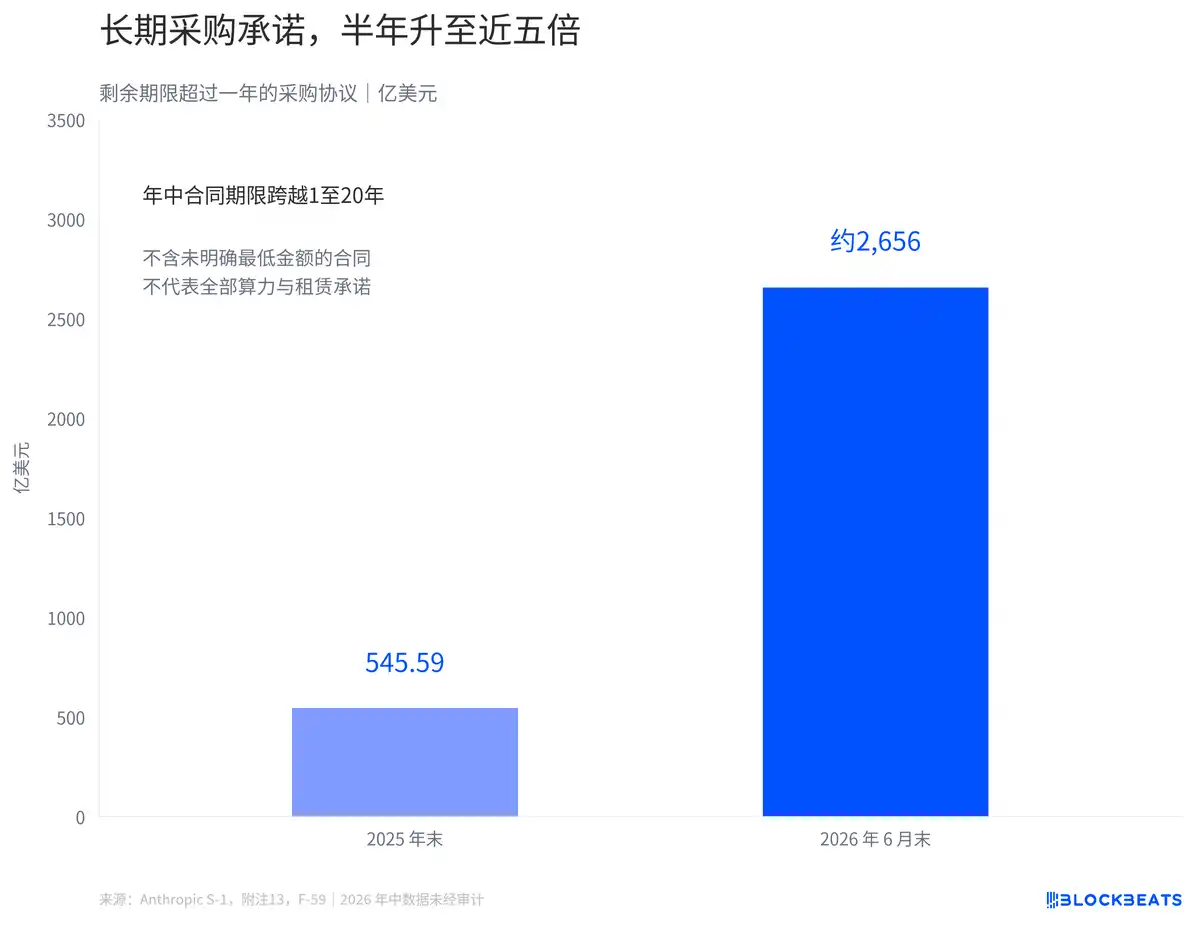
As of mid-year, the fixed or minimum guaranteed commitments under such agreements amounted to approximately $265.6 billion.
This figure also does not cover all compute expenditures. The notes explicitly state that certain agreements do not specify fixed or minimum dollar commitments—actual payments depend on delivered capacity, timing, and pricing—and therefore are not included in the above amount. Leases, purchases, and arrangements without explicit minimum amounts also cannot be aggregated into a single total without verification.
The company notes in its risk factors that its revenue is primarily usage-based, with a significant portion not protected by long-term contracts, while compute obligations often extend for multiple years. Customers can increase or decrease usage today, yet minimum payment requirements on the supply side may persist.
Second-quarter operating income answers whether current-quarter service revenue can cover operating expenses; the payment dates on multi-year purchase contracts are a separate ledger.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia
