Microsoft has not canceled Nscale's Texas computing contract, but has decided not to double it. On November 5, according to FT, Microsoft declined to exercise an option that could more than double the Texas lease, with a potential incremental value in the billions of dollars. After the news broke, Nebius and IREN fell over 16% in the afternoon, and CoreWeave dropped about 12%.
Nscale is a UK-based computing rental provider preparing for a NYSE listing, with a target valuation of $30 billion to $35 billion. It belongs to the neocloud category—new cloud providers that specialize in renting GPU computing power to major tech companies—alongside Nebius, IREN, and CoreWeave. Such companies first secure revenue with long-term contracts, then use those contracts to borrow money to build power stations and buy cards.
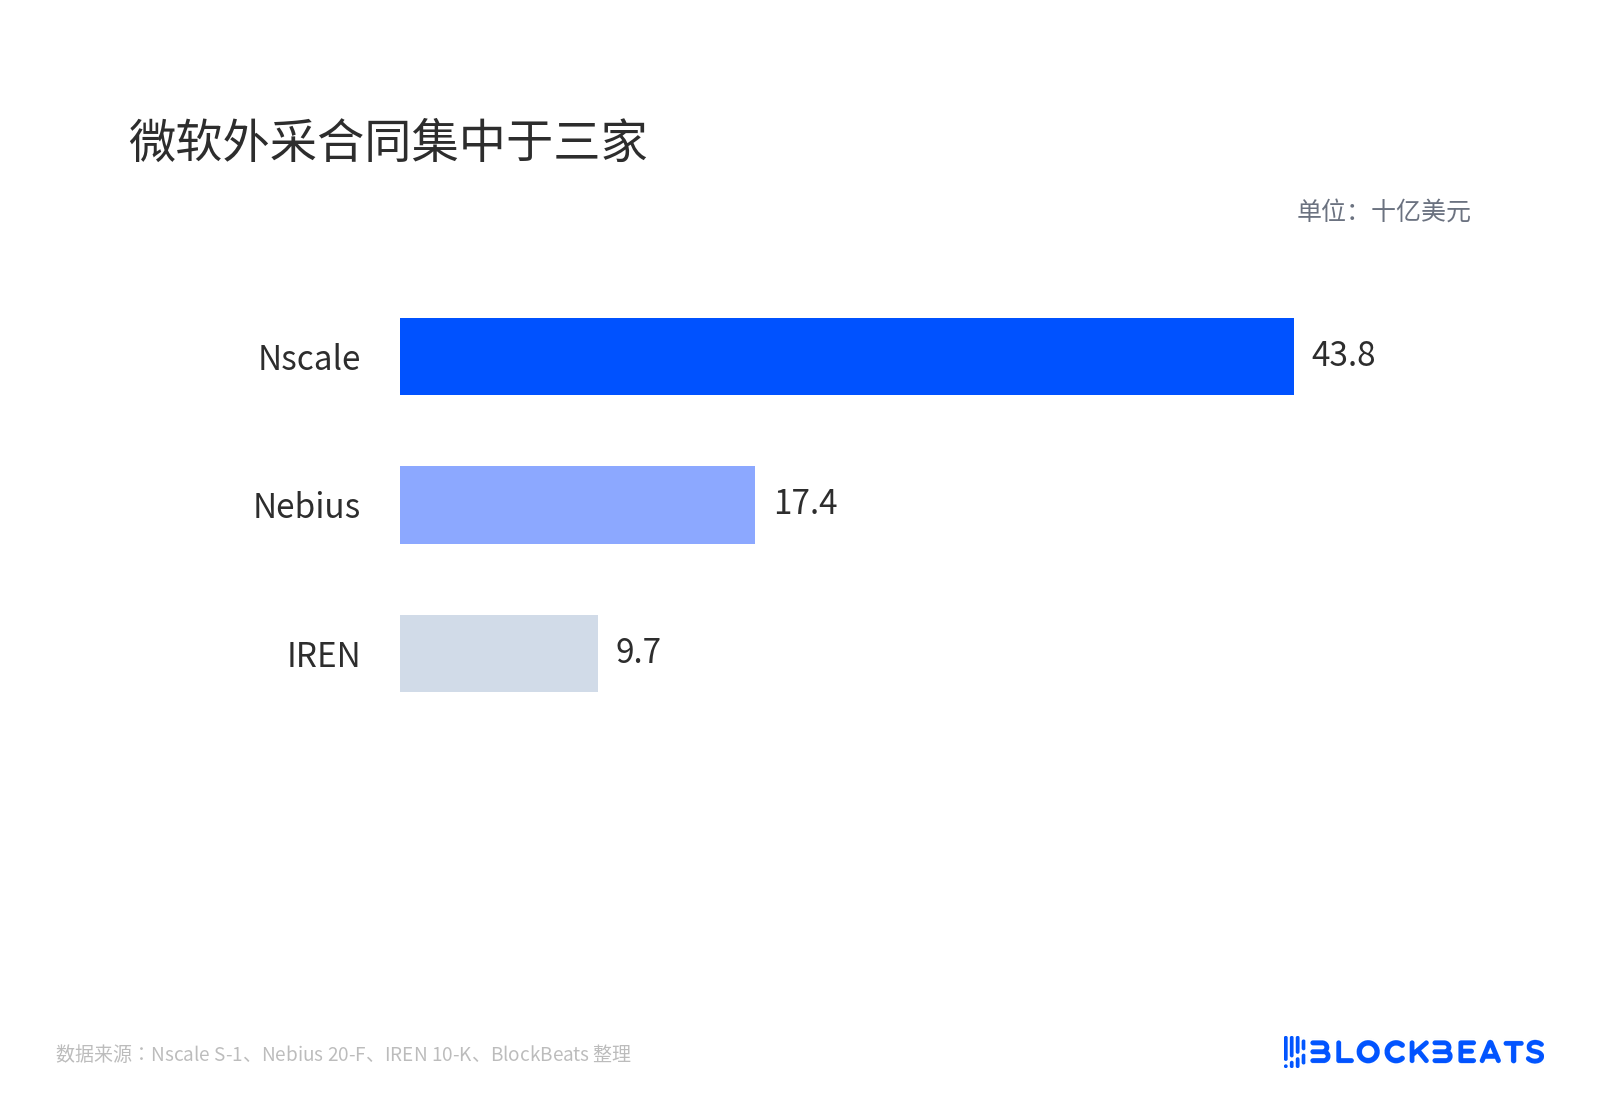
What Microsoft gave up was the expansion right
The contract therefore splits into two layers. Take-or-pay clauses that must be paid once signed count even if unused. Options are the opposite: the buyer has the right to add capacity at an agreed price but is not obligated to exercise it. The former is booked orders; the latter is growth expectation.
What Microsoft gave up is the latter. The existing Texas contract remains valid, and the site where Nscale supplies computing to Microsoft is already delivering. The company also clarified that the unexercised option is closer to 500MW, corresponding to adjacent land it owns, rather than the 700MW Phase 2 originally promoted.
But Microsoft's attitude is indeed tightening. On the same day, Bloomberg cited people familiar with the matter saying Microsoft is strengthening oversight of Nebius, IREN, and Nscale projects, with some leadership experiencing "buyer's remorse" over delivery delays and regulatory uncertainty. A Microsoft spokesperson put it more conservatively, saying the strategy remains a combination of self-built, leased, and third-party capacity.
Only $2.6 billion of $103.4 billion is running
Nscale's prospectus filed on September 18 states that as of August 31, the total active and contracted value (TCV) was $103.4 billion. This is the core selling point of the entire document and the anchor for the $30 billion to $35 billion valuation.
The same document also spells out the other side. Only $2.6 billion is actually running, accounting for 2.5%.
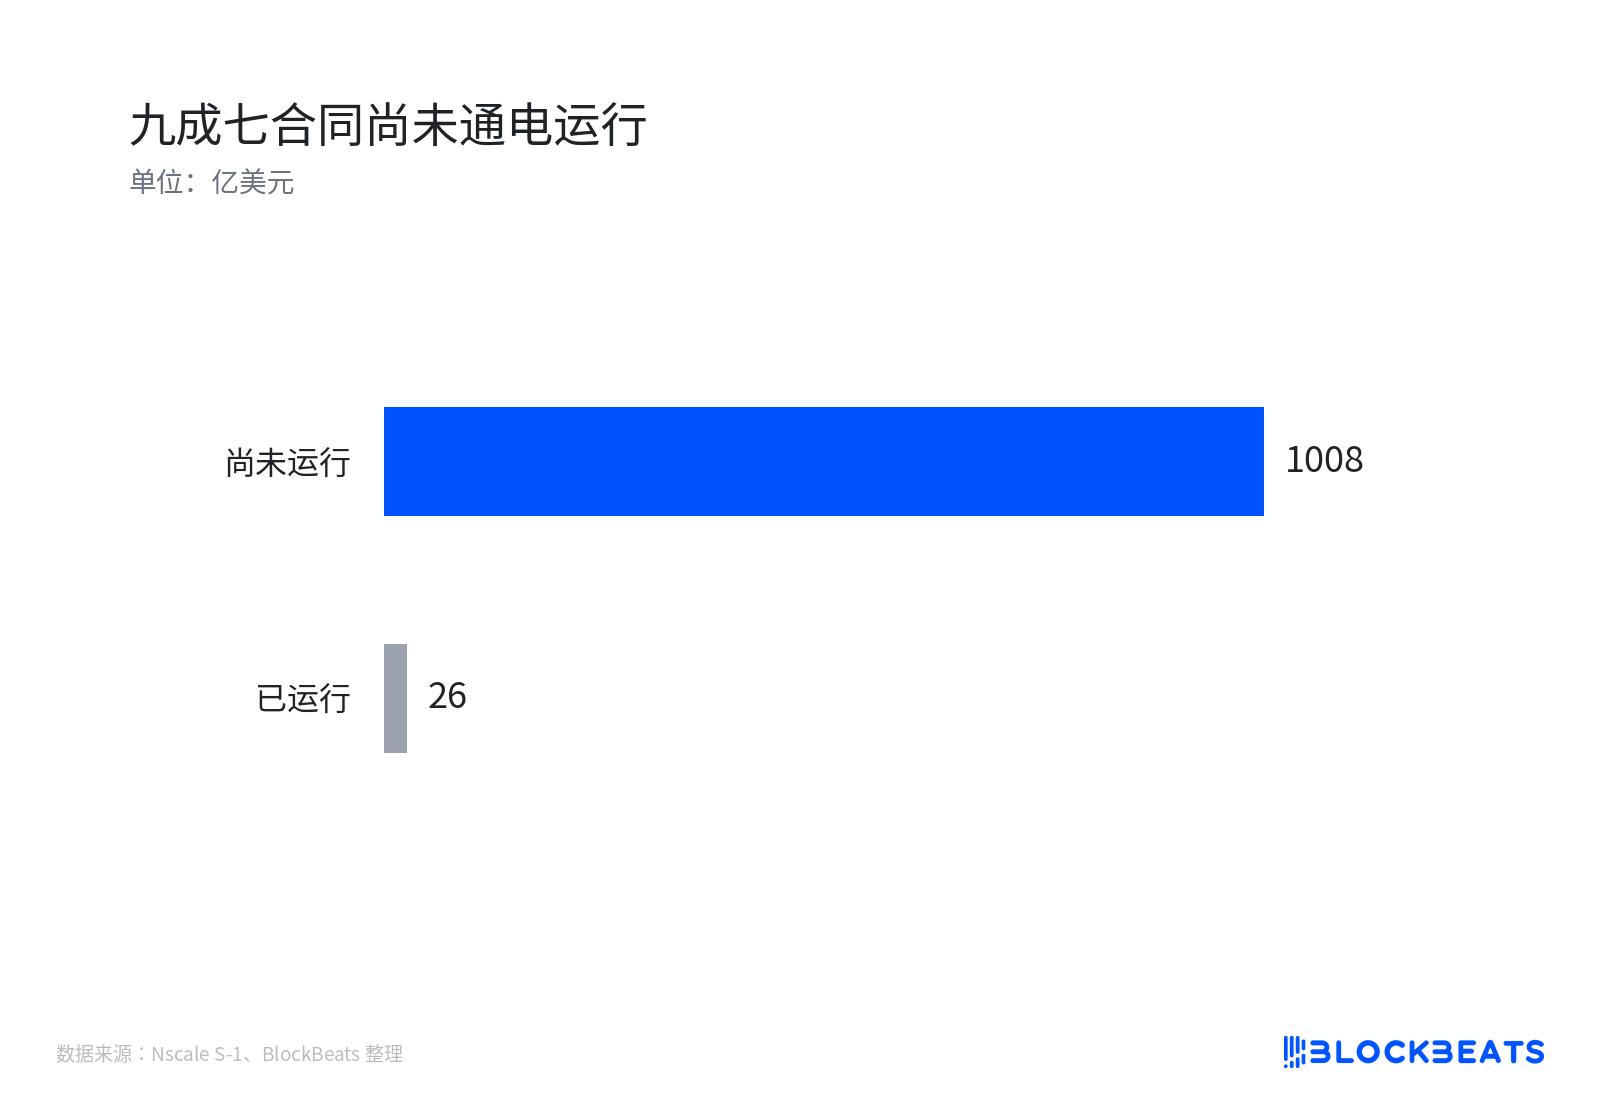
TCV only counts the full-term committed revenue of signed contracts, explicitly excluding unexercised expansion options and optional extensions.
This is precisely the crux of the controversy. The option Microsoft did not exercise, by the company's own definition, was never part of that $103.4 billion. So "order backlog shaken" strictly speaking does not hold, and "fundamentals completely unharmed" equally does not hold.
Concentration is also an open secret. Microsoft's contract cap is about $43.8 billion, Anthropic's about $44.6 billion, together accounting for 85% of TCV. In the first half of this year, Nscale's revenue was $140.6 million, with a net loss of $1.02 billion.
How much can replacement customers fill
Nscale's answer is Figure, already contracted at its own Texas site, about $3.5 billion, for 100,000 of Nvidia's next-generation Vera Rubin chips. The company also says it is in talks with other customers, including large cloud providers.
This contract proves that the Texas site is not only sellable to Microsoft, but it is not yet enough to prove it can replace that 500MW option. Price, commissioning timeline, and payment terms have not yet been disclosed.
The underestimated potential liability may lie elsewhere. Anthropic's Monarch Phase 1 project is located in West Virginia, and financing has not yet been finalized; once overdue, the contract could be terminated. Anthropic accounts for about 44% of TCV, and if this financing runs into trouble, the impact would be far greater than a missed option.
Nvidia is likewise a variable. It is both a chip supplier and provides guarantees of up to about $860 million for the lease obligations of the collaborative project Ionic, and also plans to complete the settlement of $1 billion in convertible bonds in mid-November.
Energization Timeline Determines What This $103.4 Billion Is Worth
Back to the original question: is this order attrition, or a withdrawn growth expectation? The evidence favors the latter, but markets never trade definitions—they trade expectations.
The $103.4 billion contract face value hasn't changed, and Microsoft's Texas master contract is still in place. What's changed is how much investors are willing to pay for "the portion that might become revenue in the future." When 97.5% of a company's revenue is still on the drawing board, valuation isn't determined by contract length—it's determined by energization timeline.
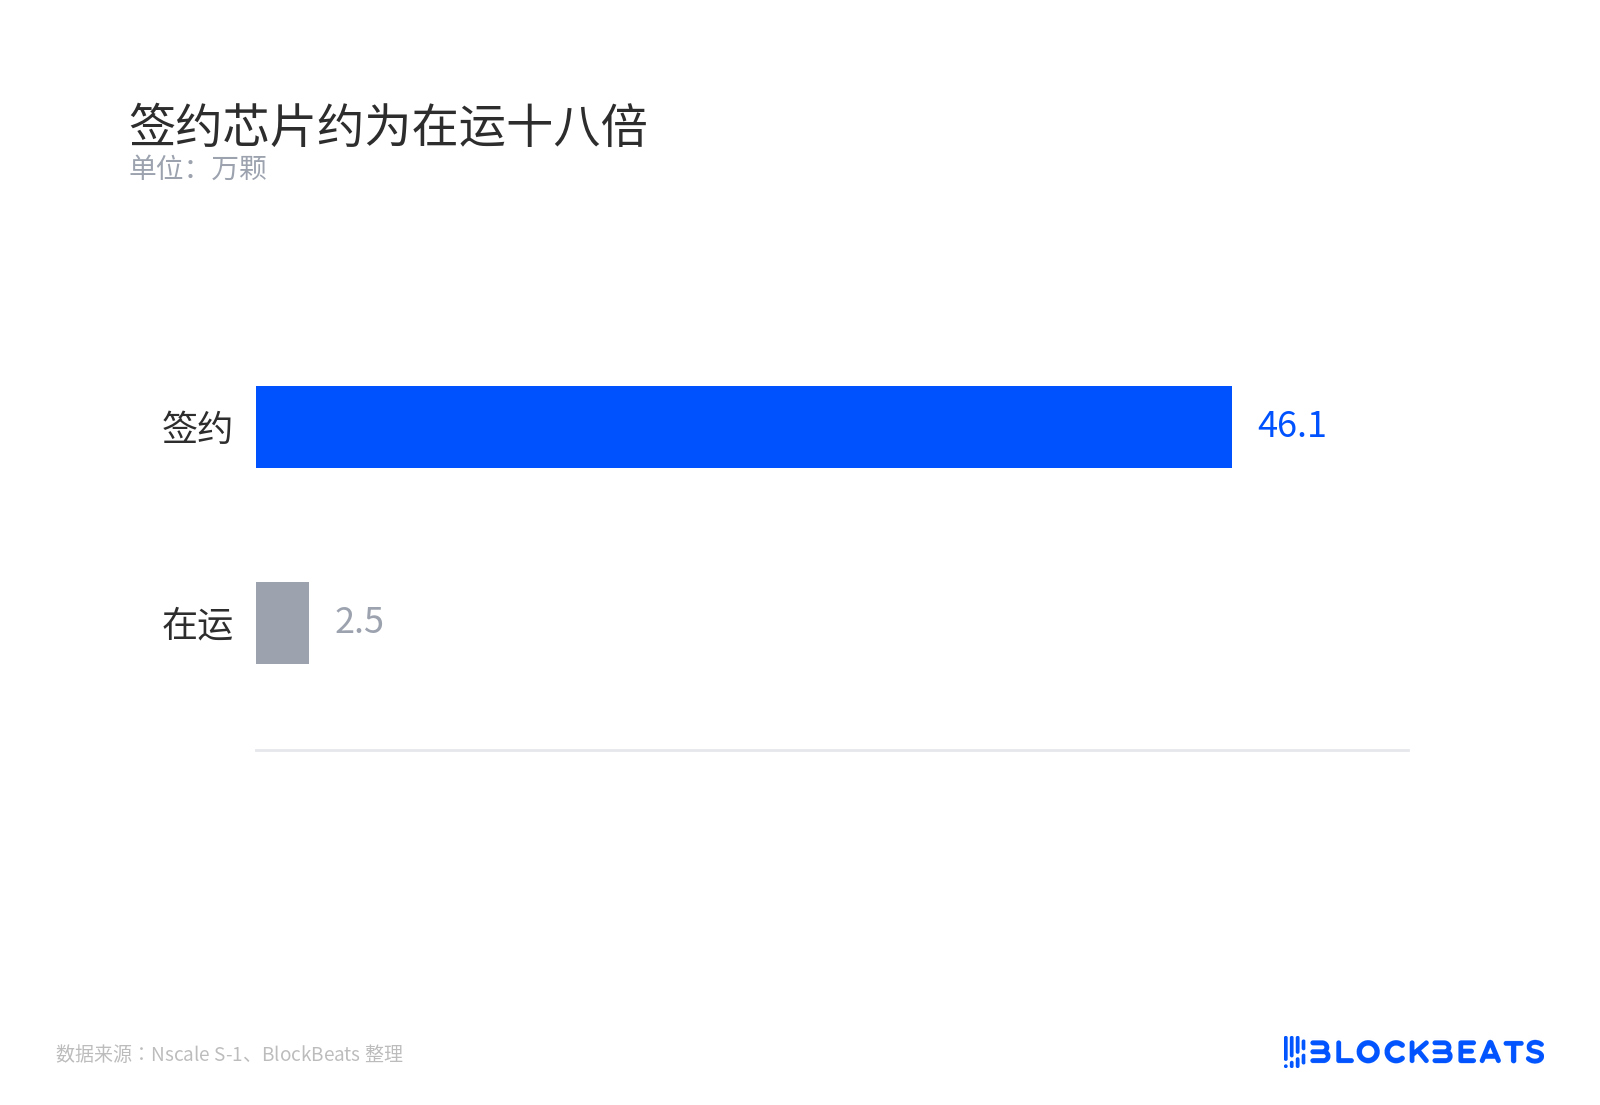
What to watch next are several specific milestones. The unit price and commissioning timeline of Figure's $3.5 billion order will determine how much cash flow that Texas site can generate. Whether Anthropic's West Virginia Phase 1 financing can be finalized on schedule will determine whether 44% of TCV can remain stable. Whether Loughton's $3 billion has been removed from TCV has not yet been publicly confirmed.
For investors holding Nebius, IREN, and CoreWeave, whether Microsoft will exit AI infrastructure is not the question to answer right now. The real question is whether, when the next "unexercised option" appears, the market will still sell first and ask questions later.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia
