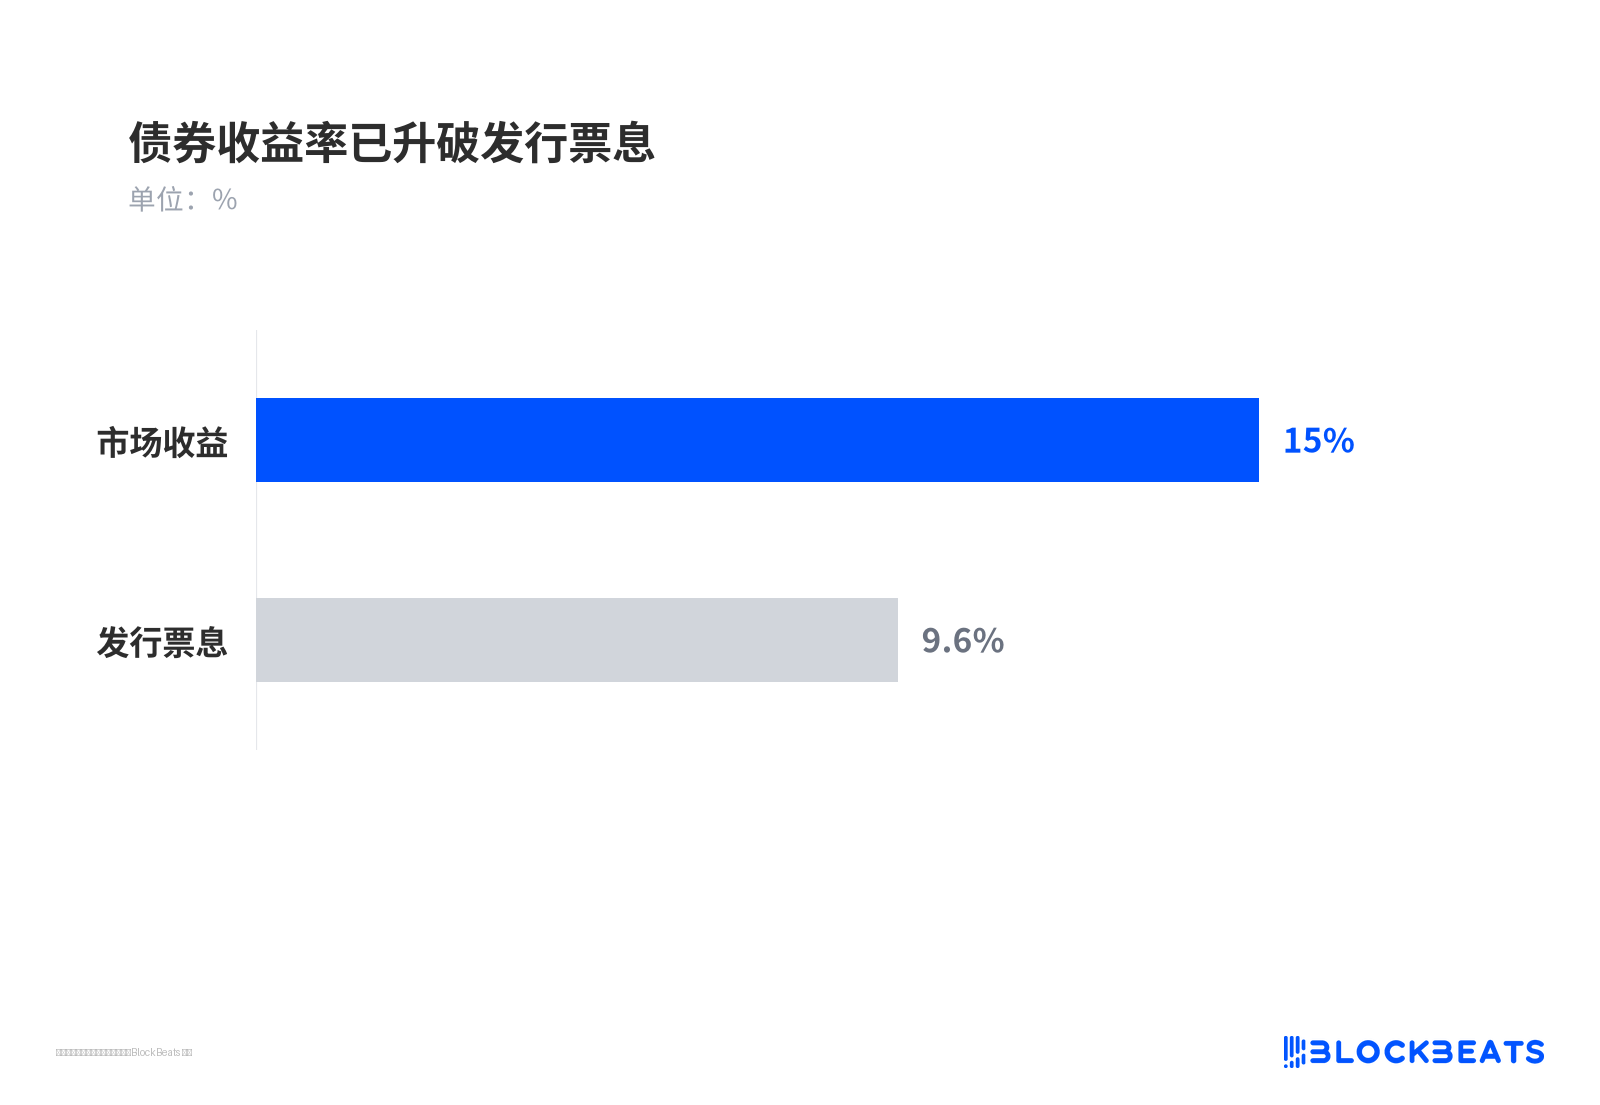
On October 18, the Financial Times cited RegLayer data stating that at least 47 large data center projects in the U.S. were delayed, withdrawn, or blocked by local opposition in 2026. In the same week, CoreWeave shares fell about 25%, and its 2031 bonds briefly yielded above 15%. The market is looking at the two together: of the $7 trillion-scale AI infrastructure plan, how much can actually connect to the grid, get leased out, and cover interest?
The market is selling the segment most dependent on external financing first. Neoclouds do not train large models; they borrow to buy GPUs and power, then lease them to customers such as OpenAI and Microsoft under multi-year contracts—essentially "compute landlords." Over the past two years, they expanded on low-interest debt, hyperscaler long-term agreements, and Nvidia backstops, treating "announcement as capacity" as the growth narrative.
The core of this repricing is not the disappearance of AI training demand. What the market is re-discounting is planning credibility, and the hit is landing on the highly leveraged execution layer. RegLayer's 47 projects and Bernstein's 35% credibility describe the physical sieve. CoreWeave's 15% bond yield describes that sieve hitting high-interest financing. Only when the two stack does the primary market begin to seize up.
Physical bottlenecks sieve out paper capacity first
Community opposition and grid connection rejections are the hardest constraints. The Financial Times counted that more than 1,000 communities this year sought moratoriums or restrictions on AI infrastructure. Bernstein believes only about 35% of the U.S. planned pipeline is credible, with bottlenecks being grid interconnection queues, 80-to-100-week lead times for transformers and switchgear, and liquid cooling systems—not capital itself.
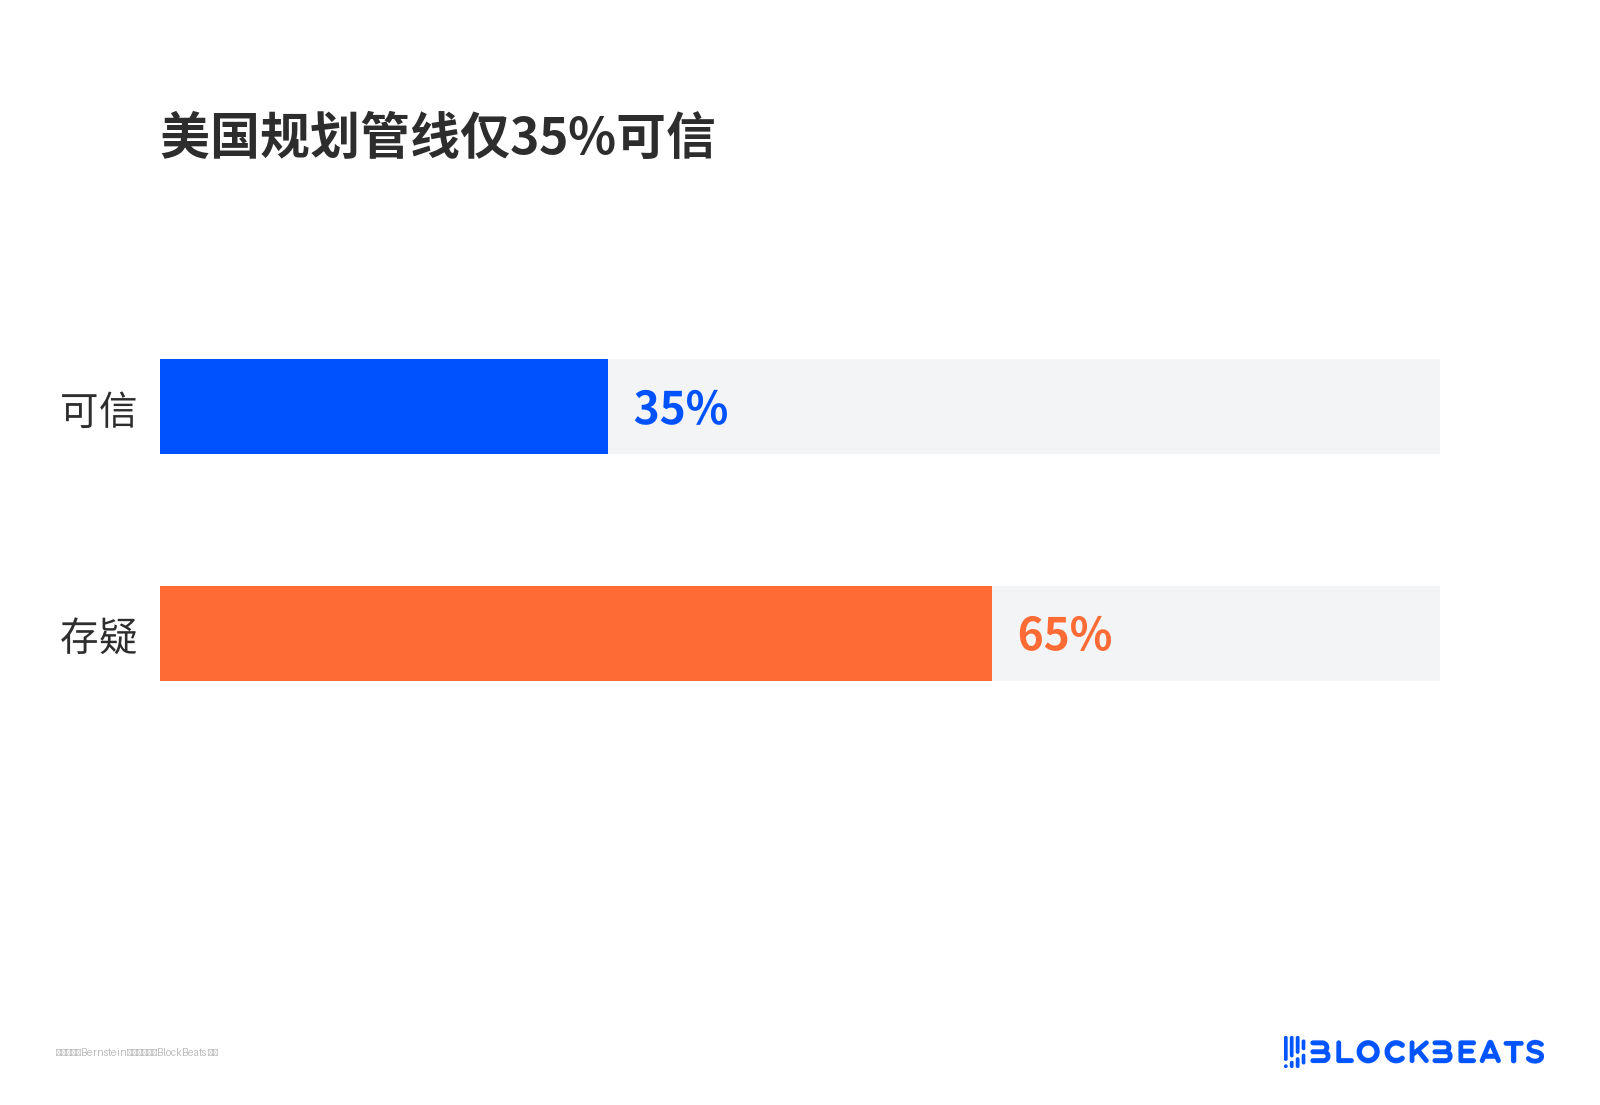
Securing financing for a project does not mean it will be built. Once grid access is denied, projects can only rely on self-generated power, which costs more and takes longer. The 47 figure is a project count, not gigawatts or dollars, and cannot be converted into an industry-wide shutdown ratio. The 35% describes planning credibility, not the share of demand that has disappeared. What it changes is investors' attitude toward announced pipelines: no longer linearly extrapolating announced GW into future supply.
CoreWeave's $100 Billion Order Book Meets 15% Bond Yield
CoreWeave is a public-market stress test. Q2 revenue was $2.58 billion, up 112% year-over-year, with a net loss of $626 million and interest expense of $640 million.
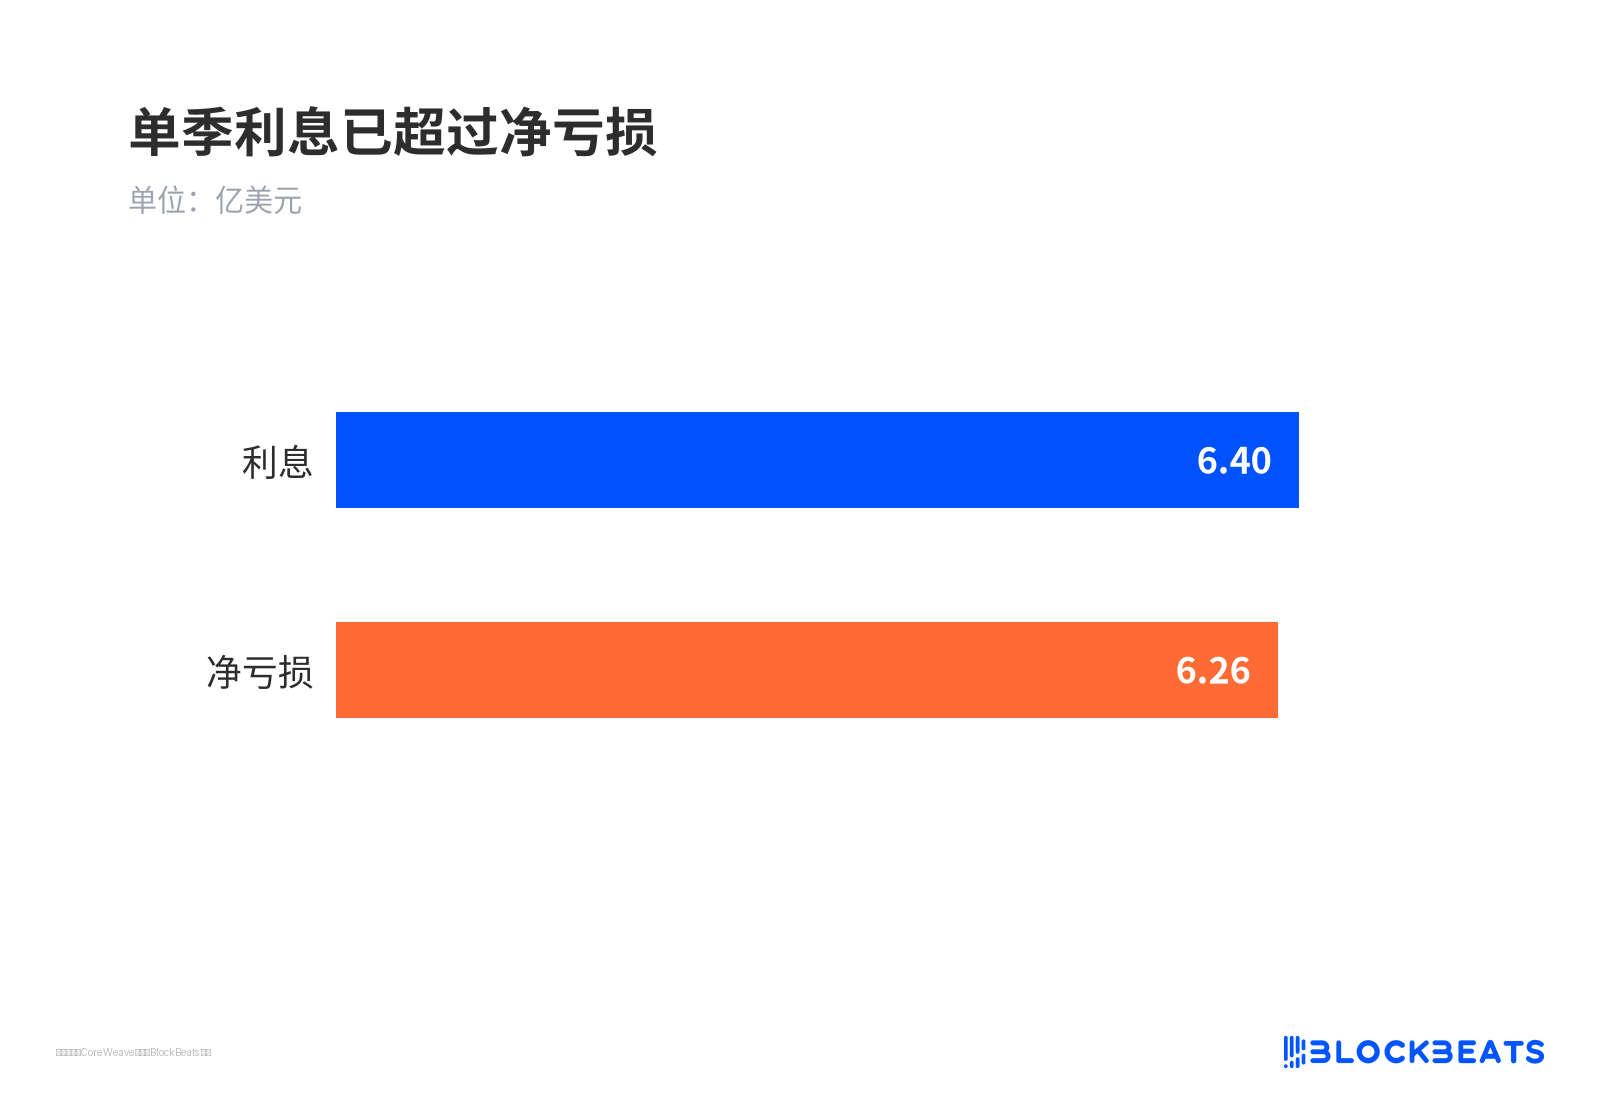
As of end-June, interest-bearing debt stood at about $35 billion, backlog at $104.2 billion, and new commitments at the start of Q3 exceeded $25 billion.
Nvidia agreed to backstop some unsold capacity, with the term extending into the early 2030s. CEO Mike Intrator said the market is "misunderstanding and irrational," and the backlog is sufficient to cover debt.
The bond market takes a shorter view. Backlog is revenue gradually recognized over the next five years, not current cash. Interest and capex must be paid now. The unlevered IRR of a five-year contract (the project's own earning power) versus the blended cost of capital (borrowing plus shareholders' required minimum return) determines whether a project pays off. A bond yield above 15% shows the market's confidence in new cloud providers' debt rollover and lease fulfillment has fallen sharply.
Goldman and JPMorgan Bet on Rollover Costs
Goldman Sachs analyst Gabriela Borges upgraded CoreWeave from Neutral to Buy on October 19, cutting the target price from $139 to $106. She believes financing risk is overpriced. Most expansion uses asset-backed loans, and the blended debt cost may rise only 100 to 200 basis points, with GPU deployment and backlog still providing support.
JPMorgan analyst Samik Chatterjee maintains Overweight, calling debt concerns "overdone." He judges that leverage comes from strong demand, not poor project economics. A typical five-year contract's unlevered IRR is in the mid-teens, above the 9% to 11% blended cost of capital, and external financing needs will persist until around 2030. The two are debating whether debt front-loads certain demand or fills a return gap with credit.
S&P and Gartner Target Off-Balance-Sheet Liabilities
Rating agencies care more about invisible debt. Mark Habib, S&P Global's head of digital infrastructure, said at an October 19 London roundtable that AI-related liabilities assumed by hyperscalers through interconnection financing "can be assumed to be more than what we see," but no rating adjustments are being made for now, and the biggest risk remains profits falling short of expectations.
Interconnection financing means Big Tech doesn't issue its own debt to build facilities, but instead signs long-term leases and provides guarantees, letting project companies borrow. On the books it doesn't look like debt for now, but in extreme scenarios it could still come back on balance sheet. Habib did not provide a size estimate.
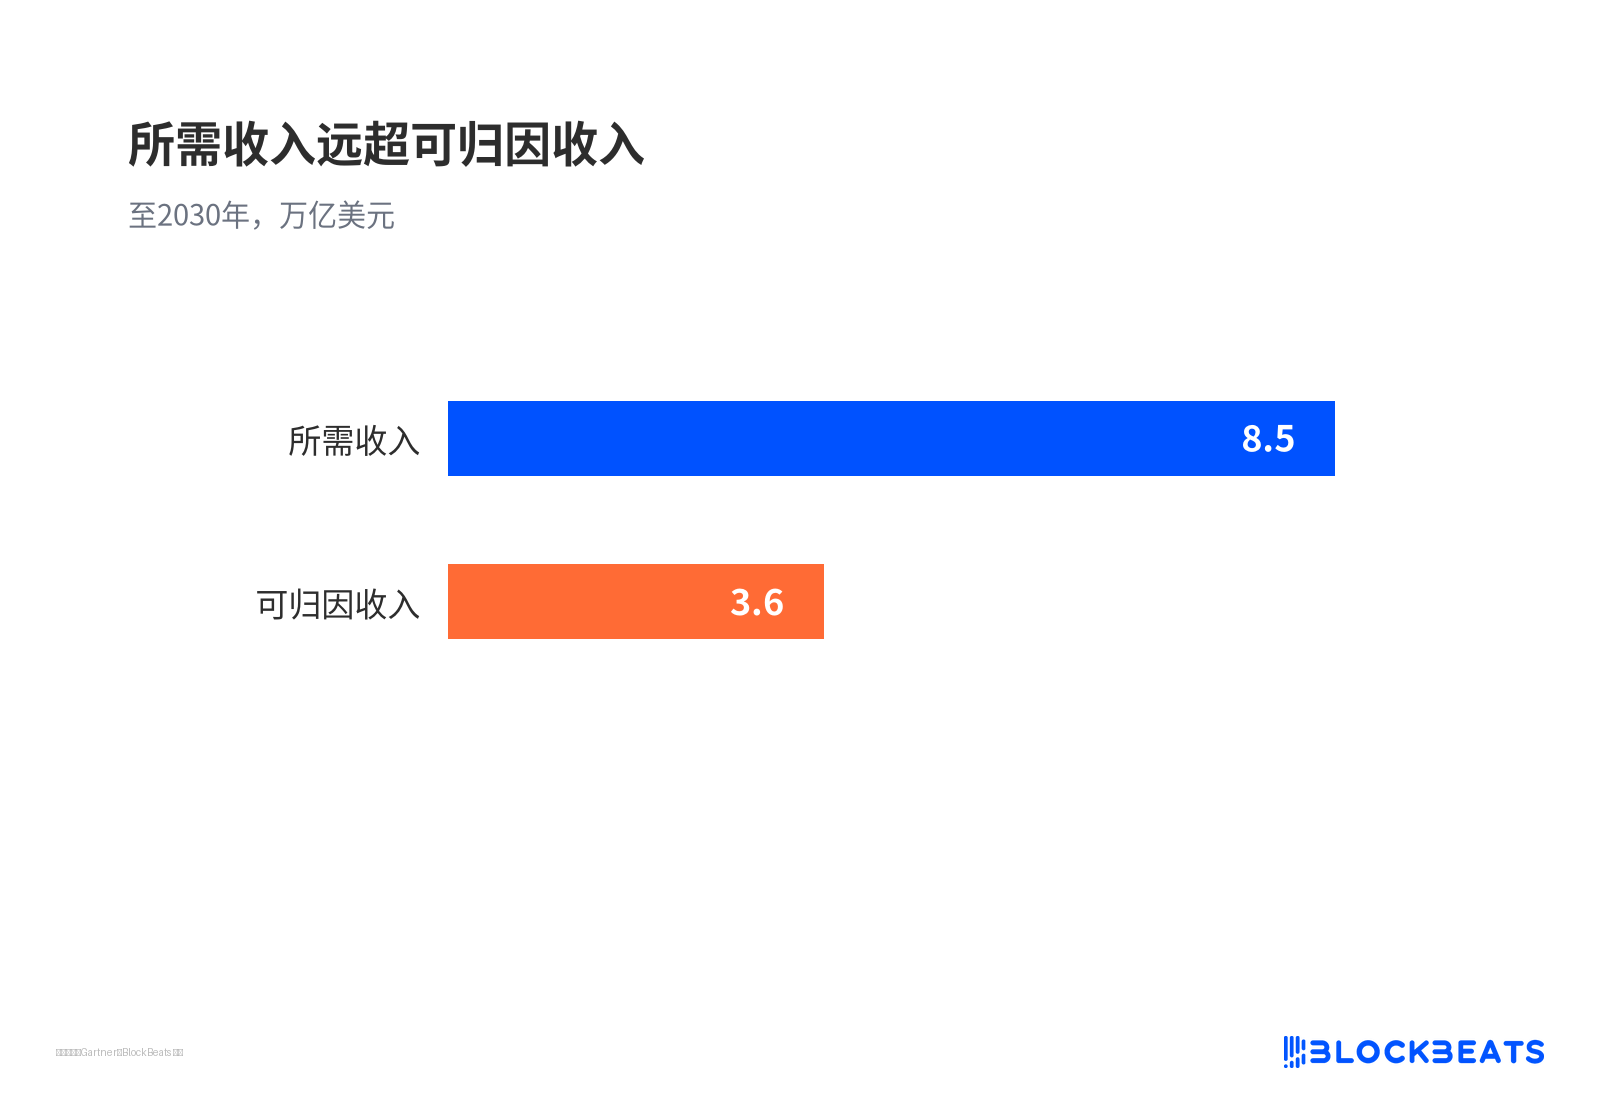
Gartner analyst Will Sommer concluded in an October 14 report that if the current pace of spending is maintained, more than $3.5 trillion in AI infrastructure spending faces impairment risk by the end of 2030. Property owners would need to accumulate $8.5 trillion in revenue to cover spending, financing costs, and achieve a 12% return on invested capital.
But attributable enterprise and consumer AI revenue does not exceed $3.6 trillion.
The report also projects that more than 80% of new cloud providers will no longer operate independently before 2030. The calculation assumes a large amount of planned spending all occurs, which may be overly strict for hyperscale cloud providers but constitutes real pressure for highly leveraged new cloud providers.
S&P expects the six major cloud providers to spend more than $7 trillion in capital expenditure from 2025 to 2030, with free cash flow remaining negative at least through 2027. The $7 trillion and Gartner's $3.5 trillion impairment risk are not on the same basis and cannot be added together.
Grid connection progress and 2027 spending determine whether it's crowding out or pass-through
Hedge funds are reducing crowding but have not fully retreated. Goldman Sachs prime brokerage shows that from October 8 to 15, hedge funds reduced tech stock holdings at the fastest pace since 2016, mainly closing longs. Net tech allocation still accounts for 23.5% of global books, at the 90th percentile of the past five years. The Nasdaq 100 fell 5.5% last week. Chips are loosening, but positioning remains heavy.
The evidence-supported conclusion is: physical constraints and credit premiums are screening out highly leveraged execution layers, rather than disproving AI training demand. Nvidia is both a supplier and a backstop for some capacity. Hyperscale cloud providers' long-term contracts and guarantees remain the anchor. What is truly unpriced is the capacity and amount of the 47 delayed projects, the 35% credibility denominator, and the off-balance-sheet liability scale cited by S&P. All three lack public quantification.
What determines direction is the six major clouds' actual execution of 2027 capital expenditure and the grid connection timetable for new projects. If spending guidance remains strong, credit repricing of new cloud providers is more likely a phased crowding-out. If guidance is cut in tandem, the adjustment will then pass upstream along project debt, GPU orders, and data center developers. The market has already discounted highly leveraged compute landlords first, but has not yet given the Big Tech that ultimately foots the bill an equivalent discount.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia
